monday.com guides to 14% growth after 19%, and its margin to 18% from 24%
monday.com’s results for July to September and its guide for the next quarter: what is slowing growth, what a 20% staff cut did to margin and cash, and what its US$36m of AI revenue counts.

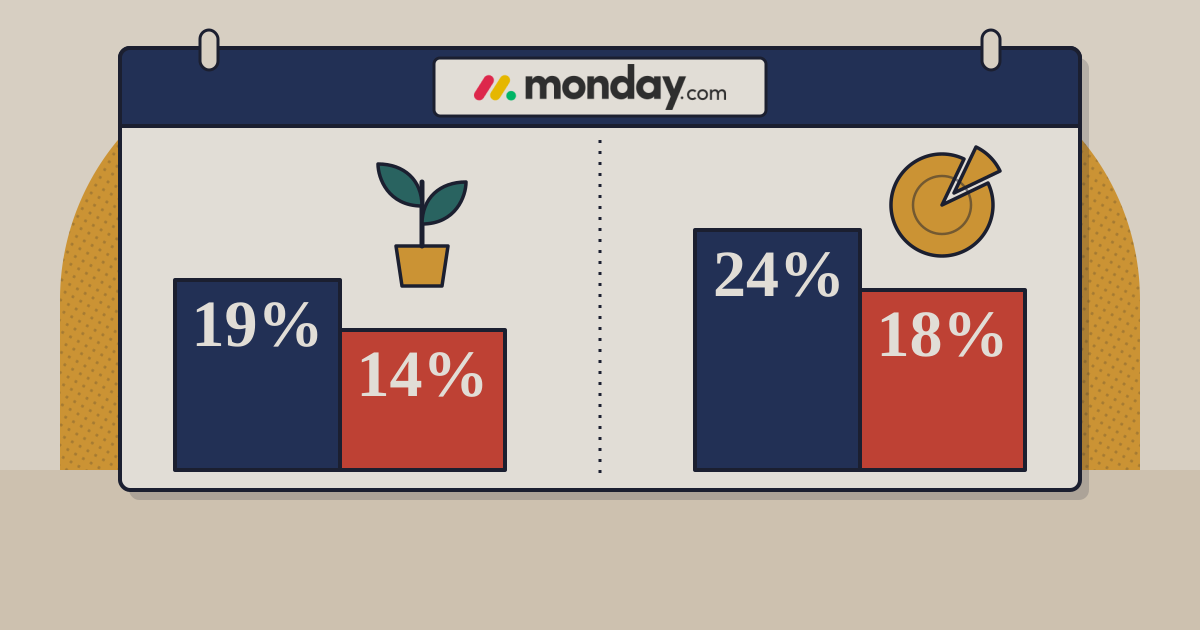
monday.com, the work-management software company, reported revenue of US$377.5m for July–September, up 19% on a year earlier, and told investors to expect about 14% in October–December: US$380m to US$382m, only US$2.5m to US$4.5m above the quarter just ended.1 Its operating margin on a non-GAAP basis, which excludes share-based pay, restructuring charges and charitable gifts of shares, is guided to about 18% after a record 24%; the GAAP margin for the quarter was 8%.1 The co-chief executives, Roy Mann and Eran Zinman, wrote that becoming an “AI-first company” “introduces near-term operational headwinds”.1
monday.com’s growth has slowed every quarter for two years, and the next step down is the largest
Revenue growth on a year earlier (%), quarters to December 2024 through September 2026, and the guide for the quarter to December 2026
%
Show tableHide table
| Revenue growth | |
|---|---|
| Q4 24 | 32 |
| Q1 25 | 30 |
| Q2 25 | 27 |
| Q3 25 | 26 |
| Q4 25 | 25 |
| Q1 26 | 24 |
| Q2 26 | 22 |
| Q3 26 | 19 |
| Q4 26* | 14 |
Source: monday.com results releases, Forms 6-K (Exhibit 99.1) · as of 9 November 2026 · * the company’s guide of about 14%; quarterly figures are as the company rounds them
01The three headwinds behind the 14%
Growth fell from 32% to 19% over the seven quarters to September, a step of one to three points each time.12345678 The guide is five. On the call Zinman named three causes: the restructuring announced in July, which cut about 20% of the workforce and was “creating some near-term disruption”; small customers, where “SMB customer additions were lower and SMB logo churn was higher”, which he said was “by design” as the company moves towards larger accounts; and “more deliberate buying behavior and longer sales cycles” as customers work out how AI fits their business.910
The picture differs by size. Net dollar retention, what existing customers pay now against a year earlier, was 108%, down from 111%; the chief financial officer, Eliran Glazer, expects 107% next quarter. Customers paying more than US$50,000 a year rose 26% and those paying more than US$100,000 rose 33%, while customers with more than 10 users rose 5%.110
The guide assumes the third quarter’s trends continue.10 It is also the company’s own number, and monday.com has lately beaten its own numbers: it guided 18% to 19% for April–June and reported 22%, and 16% to 17% for July–September and reported 19%.23 Glazer called the outlook “prudent” and said the company was “probably a few quarters from getting back to something that implies more stability”.10
02Why the margin peaks and the cash does not
Non-GAAP operating income was US$89.4m against US$47.5m a year earlier. The gain came from sales and marketing, down to US$145.4m from US$151.8m on higher revenue.1 The guide is US$68m to US$70m. Glazer said most of about US$100m of restructuring savings is being reinvested, with fourth-quarter costs carrying pay changes, AI running costs and the company’s Elevate customer event; the guide also assumes a 100 to 200 basis point hit from currency. For the full year the margin guide rises to about 18% from about 16%.1210
Operating cash flow fell to US$20.4m from US$95.1m. Most of the gap is the restructuring: US$47.2m of severance and office-exit payments went out in the quarter, and the company’s adjusted free cash flow, which adds them back, was still lower at US$63.0m against US$92.3m.1 Glazer said that cash follows ARR, and that slower net additions from small customers are holding it back.10
AI products reached US$36m of annual recurring revenue, about 2.4% of annualised quarterly revenue (our arithmetic). That counts credit packages and an allocated share of plans that include credits.1 Glazer said of the US$36m: “it’s not incremental yet. It’s part of our overall ARR.”10
The release reached the SEC at 7:00am New York time on 9 November, before the market opened. The shares closed at US$79.93 that day, down 9.1% from US$87.93, after falling 6.3% on 6 November.111 What to watch: whether net dollar retention holds at 107%, and whether the fourth-quarter costs prove to be the run rate Glazer describes.
Sources
- monday.com, Announces Third Quarter 2026 Results (6-K, Exhibit 99.1; accepted by the SEC at 7:00am New York time) — 9 November 2026
- monday.com, second quarter 2026 results (6-K, Exhibit 99.1) — 10 August 2026
- monday.com, first quarter 2026 results (6-K, Exhibit 99.1) — 11 May 2026
- monday.com, fourth quarter and fiscal 2025 results (6-K, Exhibit 99.1) — 9 February 2026
- monday.com, third quarter 2025 results (6-K, Exhibit 99.1) — 10 November 2025
- monday.com, second quarter 2025 results (6-K, Exhibit 99.1) — 11 August 2025
- monday.com, first quarter 2025 results (6-K, Exhibit 99.1) — 12 May 2025
- monday.com, fourth quarter and fiscal 2024 results (6-K, Exhibit 99.1) — 10 February 2025
- monday.com, Form 6-K on its restructuring plan — 22 July 2026
- The Motley Fool, monday.com (MNDY) Q3 2026 earnings call transcript (Roy Mann, Eran Zinman, Eliran Glazer) — 9 November 2026
- Nasdaq, monday.com (MNDY) historical prices (closes to 9 November 2026) — 9 November 2026
Disclosure. TechBag is a software reseller: it earns a margin when a reader buys through it, including from vendors named here. The analysis is TechBag’s own; no vendor paid for or saw this piece before publication. Facts are labelled reported, TechBag count or our view.
Keep reading