Amagi’s ad impressions rose 65%, revenue 27%; its 30-fold profit starts from ₹2.5 crore
Amagi’s results for July to September: how an Indian cloud company earns from TV and streaming ads, why its ad volume outgrows its revenue, and where the profit came from.

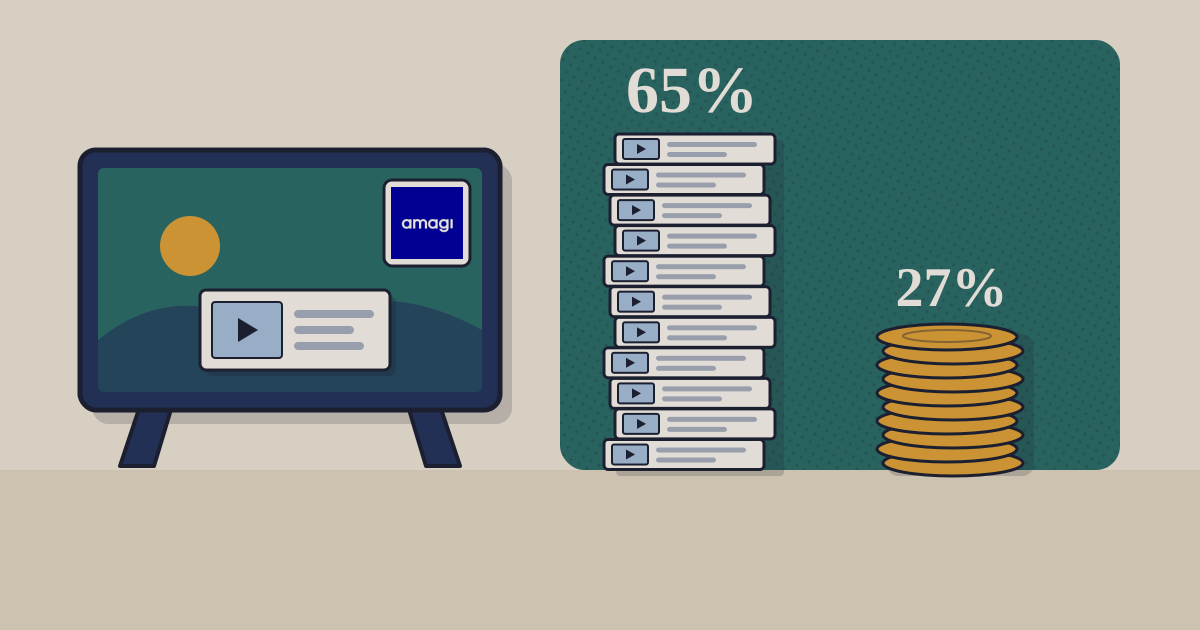
Amagi monetised 16.0 billion ad impressions in the three months to September, 65% more than a year earlier. Revenue from its ad business, Monetization & Marketplace, rose 28% to ₹119.8 crore, and revenue from operations 27% to ₹475.8 crore.1 Profit after tax rose nearly 30-fold, to ₹74.8 crore from ₹2.5 crore, the number in the company’s headline.24 That base was small: a year ago a one-time stock-option charge and a 50% tax rate left almost nothing.1
01What Amagi sells
Amagi, a Bengaluru company founded in 2008, sells cloud software that lets TV networks and streaming services “launch, manage, distribute, and monetize” channels across cable, OTT and FAST (free, ad-supported streaming TV) “without investing in traditional broadcast infrastructure”.2 It reports three businesses: Streaming Unification, putting channels on streaming platforms (₹261.1 crore, up 35%); Monetization & Marketplace, the ads; and Cloud Modernization, moving broadcasters’ playout to the cloud (₹94.9 crore, up 9%).1 Its impression count covers server-side ad insertion through THUNDERSTORM, where ads are stitched into the stream before it reaches the viewer, and workflows run by ADS PLUS. Named customers include Scripps in the US, KT Studio Genie in South Korea and NDTV in India.3
The ten largest customers paid 41.0% of the quarter’s revenue,1 and the Americas and Europe 90.1% of the year to March 2026’s.5 Amagi listed on the NSE and BSE on 21 January 2026 at ₹361 a share.4
02Why ad volume outgrows ad revenue
The gap is not new. Impressions grew 62% in the year to March 2026 and 59% in April–June, against 36% and 30% for the ad business.58
Amagi's ad volume has grown about twice as fast as its ad revenue, and the gap is widening
Year-on-year growth, %: monetised ad impressions and Monetization & Marketplace revenue, FY26 and the two quarters since
- Monetised ad impressions
- Ad business revenue
%
Show tableHide table
| Monetised ad impressions | Ad business revenue | |
|---|---|---|
| Apr 2025–Mar 2026 | 62 | 36 |
| Apr–Jun 2026 | 59 | 30 |
| Jul–Sep 2026 | 65 | 28 |
Source: Amagi Media Labs shareholder letters, Q4 FY26, Q1 FY27 and Q2 FY27 · as of 5 November 2026 · revenue growth as reported in rupees; FY = April to March
Amagi’s own documents give the reasons. Ad budgets “have not shifted from linear to CTV at the same pace as audiences, keeping CPMs under pressure in some markets” (a CPM is the price of a thousand ads), and newer channels are “still building viewership and advertiser relationships”.5 Its chief financial officer, Vijay NP, said in February that the impression count is “not one-on-one reflective” of price, because “yield, CPMs”, “contract duration and other sliding scales” come in between;7 in May he called it “modest pressure on CPMs, but that’s more than offset by the volume uptick”.6 Separately, Amagi cut its rate to “a major streaming customer” last year for a longer commitment.1
03Where the 30-fold profit came from
+₹47.5 cr
higher adjusted EBITDA (operating profit before stock options)
TechBag arithmetic
+₹19.6 cr
lower stock-option cost
TechBag arithmetic
+₹11.2 cr
more other income, mainly on IPO money
TechBag arithmetic
−₹5.2 cr
more tax, despite a 9.4% rate
TechBag arithmetic
Profit rose ₹72.3 crore; about two-thirds came from adjusted EBITDA, which more than doubled to ₹89.1 crore as overheads grew 7% against revenue’s 27%. Stock-option costs fell to ₹25.4 crore from ₹45.0 crore, but last year’s included a one-time pre-IPO catch-up; without it they were 7.3% of revenue, about ₹27 crore.1
The tax rate fell to 9.4% from 50.0%, yet the bill rose, to ₹7.7 crore from ₹2.5 crore. Its current tax was all foreign, none in India,4 where carried-forward losses absorb its profit. It says the rate “will move towards statutory rates as these losses are utilised”, and that it will assess recognising deferred tax assets on those losses “in the next few quarters”, which would be a non-cash credit. It calls the half year’s 15.3% adjusted EBITDA margin, not the quarter’s 18.7%, “a more representative near-term baseline”, because the quarter gained from the timing of planned senior hires whose cost now falls later.1
Sources
- Amagi Media Labs, Shareholder Letter Q2 FY27, filed with NSE and BSE — 5 November 2026
- Amagi Media Labs, press release on Q2 FY27 results — 5 November 2026
- Amagi Media Labs, Q2 & H1 FY27 earnings presentation — 5 November 2026
- Amagi Media Labs, unaudited consolidated results, quarter and half year to 30 September 2026 — 5 November 2026
- Amagi Media Labs, Shareholder Letter Q4 FY26 — 20 May 2026
- Amagi Media Labs, Q4 FY26 earnings call transcript (call of 21 May) — 27 May 2026
- Amagi Media Labs, Q3 FY26 earnings call transcript (call of 12 February) — 18 February 2026
- Amagi Media Labs, Shareholder Letter Q1 FY27 — 13 August 2026
Disclosure. TechBag is a software reseller: it earns a margin when a reader buys through it, including from vendors named here. The analysis is TechBag’s own; no vendor paid for or saw this piece before publication. Facts are labelled reported, TechBag count or our view.
Keep reading