Markets & the AI economyAnalysis
Blackstone’s BXDC buys 75% of 13 AWS data centres at US$5bn; Amazon will rent them back
What BXDC’s filings of 16 November show: 647 MW in Indiana and Mississippi, about US$350m of first-year rent rising 2.75% a year, and at least US$4.33bn of cash for Amazon.

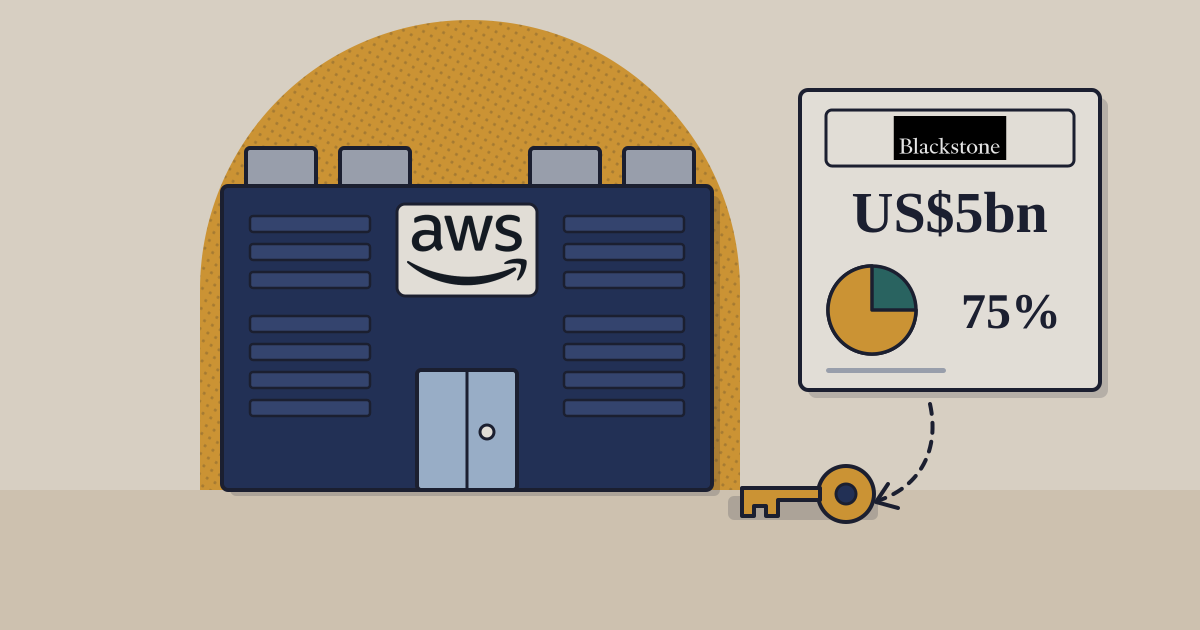
BXDC listed on the New York Stock Exchange in May with about US$2bn from investors and no buildings: a trust set up to own newly built data centres leased to the largest cloud companies on long contracts, run by a Blackstone affiliate.67 On 16 November it named its first purchase, and the seller is also the tenant. This piece reads the filings to answer three questions: what exactly BXDC is buying, how the money moves from a REIT’s shareholders and lenders to Amazon, and what has to happen before 31 December for it to close.
01Thirteen buildings, 647 MW, one tenant
The contribution agreement was signed on 11 November and disclosed in an 8-K filed before the market opened on 16 November. Two BXDC subsidiaries will take a 75.1% controlling interest in two joint ventures, one per campus. Amazon Data Services, a significant subsidiary of Amazon.com, puts the buildings into the joint ventures in exchange for the remaining 24.9% and a cash distribution, then leases 100% of both campuses back under triple-net leases guaranteed by Amazon.com itself.1
One campus has nine buildings in St. Joseph County, northern Indiana, which BXDC counts as part of the greater Chicago data-centre market; the other has four buildings in Madison County, Mississippi. More than two-thirds of the value is in Indiana, and the buildings’ average construction year is 2026.46 BXDC calls them “powered shells”: the buildings and their power supply, with the data halls designed to house the tenant’s racks and the mechanical and electrical plant that supports them, in the agreement’s definition of a room.24
BXDC's first purchase: US$5.0bn for 13 buildings leased to one tenant
Headline terms of the BXDC-AWS transaction, at 100% of the joint ventures, signed 11 November 2026
US$5.0bn
gross value, including transaction costs; BXDC buys 75.1%
647 MW
IT power capacity in 13 newly built buildings
7.0%
initial cap rate: first-year base rent over the value
12 / 32
years of lease, initial / with two 10-year renewals
Source: BXDC 8-K Item 1.01 and transaction summary (16 Nov 2026) · as of 16 November 2026
The leases carry a fixed 2.75% annual rent increase. Under a triple-net lease the tenant pays the running costs, including power, property taxes and insurance; BXDC’s form lease leaves the landlord with certain structural items such as the roof.17 BXDC’s summary describes the guarantor as a “high investment grade cloud provider (S&P AA)”.4
02How the money moves: at least US$4.33bn to Amazon
A sale-leaseback swaps ownership for cash while the seller keeps using the property. The agreement does it through the joint ventures rather than a straight sale, in four steps that all happen at closing:2
Amazon puts in the buildings and takes out the cash, then pays rent to the venture it partly owns
Steps at closing under the contribution agreement of 11 November 2026
- 01
Contribute
Amazon’s subsidiary deeds both campuses into two joint ventures, each owned through a bankruptcy-remote chain of companies.
- 02
Fund
BXDC puts in about US$1.9bn of IPO cash for 75.1%; the ventures borrow about US$2.5bn of non-recourse mortgage loans.
- 03
Distribute
The ventures pay Amazon’s side at least US$4.33bn. It keeps 24.9%, valued at about US$0.6bn.
- 04
Lease back
Amazon rents 100% of both campuses, triple-net, for 12 years with options to 32, rent rising 2.75% a year.
Source: BXDC 8-K Item 1.01 and Ex-2.1, Contribution Agreement, sections 1.2 and 6.1 (16 Nov 2026) · as of 16 November 2026
US$4.33bn
the minimum cash distribution to Amazon's side at closing, set in the contribution agreement
US$4,328,452,478, subject to loan-sizing adjustments and Amazon’s share of closing costs: 87% of the US$5.0bn value.
The agreement makes that minimum a condition of Amazon’s obligation to close.2 Amazon has not said what the cash is for. AWS’s vice-president of infrastructure, Prasad Kalyanaraman, said in the release that “partnering with Blackstone allows us to continue expanding responsibly while keeping communities at the center of how we build.”3 Amazon’s own results show the scale it is building at: US$77.3bn spent on property and equipment in the quarter to 30 September, free cash flow of minus US$42.4bn over twelve months, US$115.1bn raised in long-term debt in the first nine months of 2026, and about US$220bn of cash capital spending expected for the year.8
03Who pays for the US$5.0bn
Half the value is borrowed. The 8-K puts the new mortgage loans at about US$2.5bn, secured on the buildings and without recourse to BXDC. BXDC’s US$1.9bn is, in its words, the “cash proceeds the Company received in its initial public offering”, and Amazon’s retained 24.9% is valued at US$0.6bn.1
Half of the US$5.0bn is mortgage debt; BXDC's IPO cash covers 38%
Sources of the transaction's gross value, US$bn, as disclosed on 16 November 2026
Source: BXDC 8-K Item 1.01 (16 Nov 2026) · as of 16 November 2026 · Amounts are the filing's rounded figures; shares of the total are our arithmetic
The IPO priced on 13 May at US$20 a share; trading began on 14 May, and with the underwriters’ extra shares on 20 May gross proceeds reached US$2.01bn for 100,619,900 shares, or US$1.9bn after fees. On 30 September BXDC held US$1.96bn in cash and had not bought a building; its only income was US$18.9m of interest in the quarter, for net income of US$15.6m.56
Three terms decide who carries the risk before closing. There is “no financing contingency”: if the loans are not funded, BXDC must close anyway and pay its share “in full from equity sources”. A party that fails to close when required pays the other a US$150m termination fee as the sole remedy. And the debt sits at about 50% of value, while the prospectus set a targeted maximum loan-to-value ratio of about 40% at the time of financing, which it said it may exceed.27 BXDC also has a US$1.0bn revolving credit line, undrawn on 30 September.6
04What the rent pays: about US$4.9bn over the first 12 years
BXDC defines the 7.0% initial cap rate as the first year’s base rent divided by the gross value, transaction costs included. On US$5.0bn that puts first-year rent at about US$350m. With the 2.75% annual increase, it reaches about US$472m in the twelfth year, and the initial term adds up to about US$4.9bn, close to what the buildings are valued at today.4
Rent starts near US$350m and passes US$470m by the twelfth year
Annual base rent over the initial lease term, US$m, at 100% of the joint ventures
US$m
Show tableHide table
| Base rent | |
|---|---|
| Yr 1 | 350 |
| Yr 2 | 360 |
| Yr 3 | 370 |
| Yr 4 | 380 |
| Yr 5 | 390 |
| Yr 6 | 401 |
| Yr 7 | 412 |
| Yr 8 | 423 |
| Yr 9 | 435 |
| Yr 10 | 447 |
| Yr 11 | 459 |
| Yr 12 | 472 |
Source: BXDC transaction summary (16 Nov 2026); TechBag arithmetic · as of 16 November 2026 · 7.0% of US$5.0bn in year 1, then +2.75% a year; renewal-period rent is not disclosed
The price per megawatt is where the powered-shell structure shows. US$5.0bn for 647 MW is about US$7.7m per MW, or about US$385m per building. BXDC’s prospectus sized its target purchases on an assumed “$15,000,000 per MW average acquisition cost”, about twice this deal’s figure, and set a target yield of 5.75% to 7.00% or higher. At 7.0%, this deal sits at the top of that range, which BXDC’s summary attributes to the “powered shell structure”.47
Importantly, it highlights our ability to source unique investment opportunities as well as the evolution of our investible universe, as the hyperscaler sale-leaseback channel doubles our total addressable market.
BXDC’s manager, a Blackstone affiliate, waived its fees through 15 November 2026. From then the trust pays it 1.00% a year of its market capitalisation up to US$25bn, plus an incentive fee.6
05What has to happen before 31 December
The agreement sets an outside closing date of 31 December 2026, which Amazon may extend in limited cases such as title problems or damage to a building, and closing happens ten business days after one condition in particular is met. That condition is Amazon’s alone: confirmation from the SEC’s staff that the deal “will not require consolidation of the Joint Ventures” by Amazon “for financial reporting purposes under applicable U.S. GAAP”. If the staff decline, both sides must negotiate changes and resubmit.2
From IPO to first purchase in six months, with 45 days left to close
BXDC's listing and the AWS transaction, May to December 2026
Show tableHide table
| Date | Event | Detail |
|---|---|---|
| 13 May 2026 | IPO priced at US$20 | 87.5m shares; trading on the NYSE from 14 May |
| 20 May 2026 | Extra shares sold | Gross proceeds US$2.01bn; US$1.9bn net |
| 30 Sept 2026 | US$1.96bn in cash | No data-centre asset yet |
| 11 Nov 2026 | Agreement signed | 75.1% of two AWS campuses at US$5.0bn |
| 16 Nov 2026 | Deal and Q3 results disclosed | Manager's fee waiver ended the day before |
| 31 Dec 2026 | Outside closing date | US$150m fee for a party that fails to close |
Source: BXDC 10-Q, 8-Ks and Contribution Agreement (16 Nov 2026); prospectus (15 May 2026) · as of 16 November 2026
BXDC’s other conditions are routine for a property deal: title insurance, representations that still hold, and no order blocking the transfer. If construction listed in the agreement is unfinished at closing, Amazon must complete it at no cost to the ventures, and it may push the closing date (not past the outside date) until each building reaches a completion standard whose definition is redacted.2
Once closed, BXDC’s own 10-Q spells out the concentration: it will “depend on one tenant with two leased properties for substantially all of our revenue”. It names local risk in both counties: in December 2025 the St. Joseph County council voted against rezoning about 1,057 acres of farmland for a proposed US$12bn data centre, and during 2026 several Mississippi cities changed their zoning rules for data centres, including a moratorium.6 On the other side, BXDC’s summary cites SemiAnalysis figures showing Indiana’s built data-centre capacity rising from 1,426 MW in 2026 to a forecast 4,722 MW in 2028, against Illinois’s 1,605 MW to 3,071 MW.4
Sources
- Blackstone Digital Infrastructure Trust: Form 8-K, Item 1.01 (Contribution Agreement) — 16 November 2026
- BXDC 8-K Exhibit 2.1: Contribution Agreement among Jade IN Member LLC, Jade MS Member LLC, Jade SMIN LLC and Jade SMMS LLC — dated 11 November 2026, filed 16 November 2026
- BXDC 8-K Exhibit 99.1: Blackstone Digital Infrastructure Trust Announces $5 Billion Acquisition of Stabilized Data Center Portfolio — 16 November 2026
- BXDC 8-K Exhibit 99.2: Transaction Summary — 16 November 2026
- BXDC 8-K Exhibit 99.1: Blackstone Digital Infrastructure Trust Reports Third-Quarter 2026 Results — 16 November 2026
- BXDC: Quarterly report on Form 10-Q for the quarter ended 30 September 2026 — 16 November 2026
- BXDC: Final prospectus (Form 424B4) for the initial public offering — 15 May 2026
- Amazon.com: Third-quarter 2026 results (8-K, Exhibit 99.1) — 29 October 2026
- Yahoo Finance: BXDC daily and intraday price data — 13 and 16 November 2026 Quote data, not a primary source; intraday price at 16:18 UTC on 16 November.
- Amazon India: Amazon plans to invest $48 billion in India through 2030 — 25 June 2026
Disclosure. TechBag is a software reseller: it earns when companies buy through it, including from vendors named here. The analysis is TechBag’s own; no vendor paid for or saw this piece before publication. Facts are labelled reported, TechBag count or our view.
Keep reading