Five9 pays US$325m cash for Level AI, about 11× next year's ARR
Five9’s merger filing, deal release and third-quarter results of 5 November: what Level AI sells, how a deal with no break fee works, and why the shares fell.

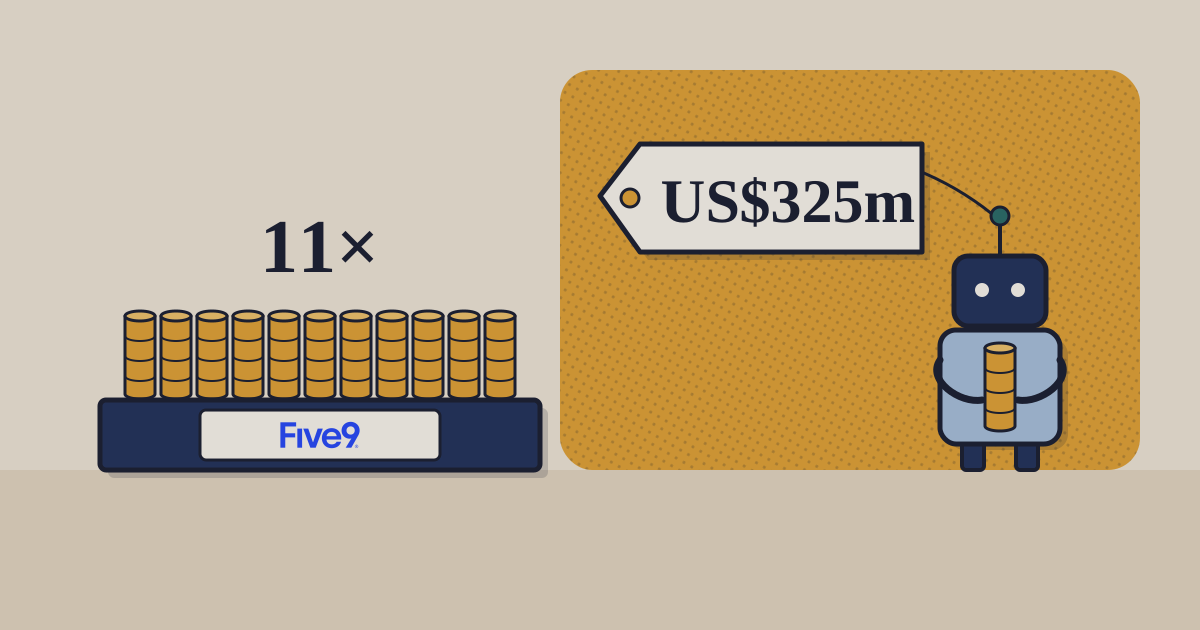
Five9, which sells cloud software for running contact centres, agreed on 5 November to buy Level AI for US$325.0m in cash, before adjustments for Level AI’s cash, debt, deal expenses and working capital at closing.1 Level AI’s annual recurring revenue is about US$20m and grew about 50% in a year, the chief financial officer, Bryan Lee, said on the call; he put the price at “approximately 11x based on next 12 months ARR.”8 The same evening Five9 reported third-quarter revenue up 13% to US$323.3m, with subscription revenue up 16%.3 Its shares fell 19.8% to US$27.40 in trading straight after the release, StockStory reported.9
US$325m
in cash, before closing adjustments
Five9 8-K, 5 Nov
~US$20m
Level AI's annual recurring revenue, up about 50%
said on the call
~11×
the price over the next twelve months' ARR
said on the call
US$0
termination fee, payable by either side
Five9 8-K, 5 Nov
01What Five9 is buying, in its own words
Level AI sells AI agents, agent assist, quality management, coaching and “Voice of the Customer” analysis on one layer that reads customer conversations, running on its own family of models, Level AI Latitude. It handles more than one billion customer interactions a year, for customers including Gusto, Chime, Empyrean and VistaPrint, and is backed by Adams Street Partners, Battery Ventures and Eniac Ventures. The two companies have worked together since 2022, through Five9’s marketplace.2
The reason Five9 gives is reach. The applications will be sold inside its own platform and also on their own, to companies “not yet ready to move their on-premises contact centers to the cloud” and to those on rival clouds.2 “Standalone AI is an attractive business in its own right, whether or not those customers eventually adopt Five9 CCaaS,” the chief executive, Amit Mathradas, said on the call. Lee said the deal would take about one point off the adjusted EBITDA margin in 2027, that Level AI should reach break-even in about six months, and that the 2026 guidance leaves Level AI out.8
The pricing matters for what is being bought. Five9 charges its monthly subscriptions “primarily based on the number of licenses”, one per agent, while its AI is sold by consumption; its 10-Q lists the risk that AI handles more interactions and licence revenue falls.5 AI revenue was about US$45m in the quarter, 17% of subscription revenue against 10% a year earlier, Lee said; concurrent seats grew “relatively in line” with contact-centre revenue.8
02A deal with no break fee
In a takeover of a listed company, a break fee is what one side pays if the deal falls away for reasons the contract names: in ADT’s US$15.3bn sale to Thrive Holdings, ADT pays US$227m in specified cases and the buyer US$473m if it fails to close when required.14 Here “neither party is required to pay a termination fee”. Either side can end the agreement if the deal has not closed by 5 February 2027, or if the other breaches it and does not cure the breach. There is no shareholder vote to win: Level AI holders with enough votes signed support agreements, and once they deliver written consent no further approval is needed.1 Five9 expects to close in the fourth quarter and to pay from cash on hand and marketable investments.35
Sources
- Five9, Form 8-K, Item 1.01: Agreement and Plan of Merger with Ujwal, Inc. (d/b/a Level AI) — 5 November 2026
- Five9, Five9 to Acquire Level AI, Advancing AI-Powered CX Platform (8-K, Exhibit 99.1) — 5 November 2026
- Five9, Five9 Announces Third Quarter 2026 Financial Results (8-K, Exhibit 99.1) — 5 November 2026
- Five9, supplemental metric disclosure, Q1 2024 to Q3 2026 (8-K, Exhibit 99.2) — 5 November 2026
- Five9, quarterly report on Form 10-Q, quarter to 30 September 2026 — 5 November 2026
- Five9, Five9 Announces Second Quarter 2026 Financial Results (8-K, Exhibit 99.1; previous full-year guidance) — 6 August 2026
- Five9, fourth quarter 2025 results release (8-K, Exhibit 99.1) — 19 February 2026
- The Motley Fool, Five9 (FIVN) Q3 2026 earnings call transcript (Amit Mathradas, Bryan Lee) — 6 November 2026
- StockStory (via FinancialContent), Five9's Q3 2026 sales top estimates but stock drops 19.8% — 5 November 2026
- Investing.com, DA Davidson cuts Five9 stock price target on acquisition concerns — 6 November 2026
- Investing.com, Needham reiterates Buy on Five9 stock after strong AI growth — 6 November 2026
- Nasdaq, FIVN historical prices (closes, 4 and 5 November 2026) — 5 November 2026
- Five9, first quarter 2026 results release (8-K, Exhibit 99.1) — 30 April 2026
- ADT, Form 8-K, Item 1.01: Agreement and Plan of Merger with Abode Parent, LLC (termination fees) — 29 October 2026
Disclosure. TechBag is a software reseller: it earns a margin when a reader buys through it, including from vendors named here. The analysis is TechBag’s own; no vendor paid for or saw this piece before publication. Facts are labelled reported, TechBag count or our view.
Keep reading